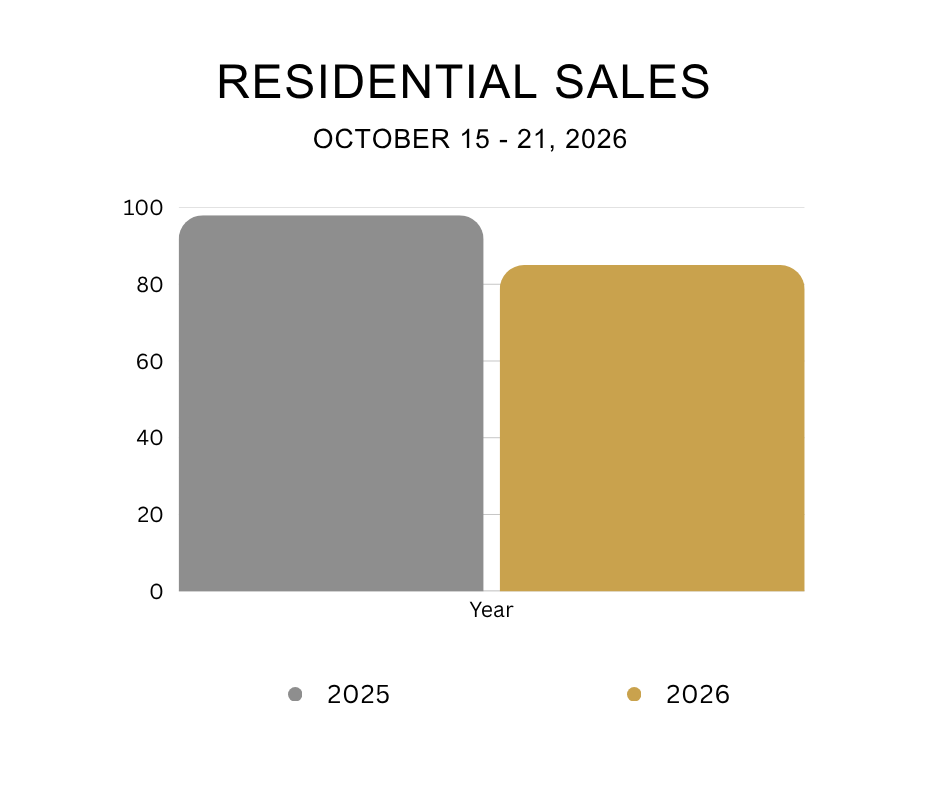
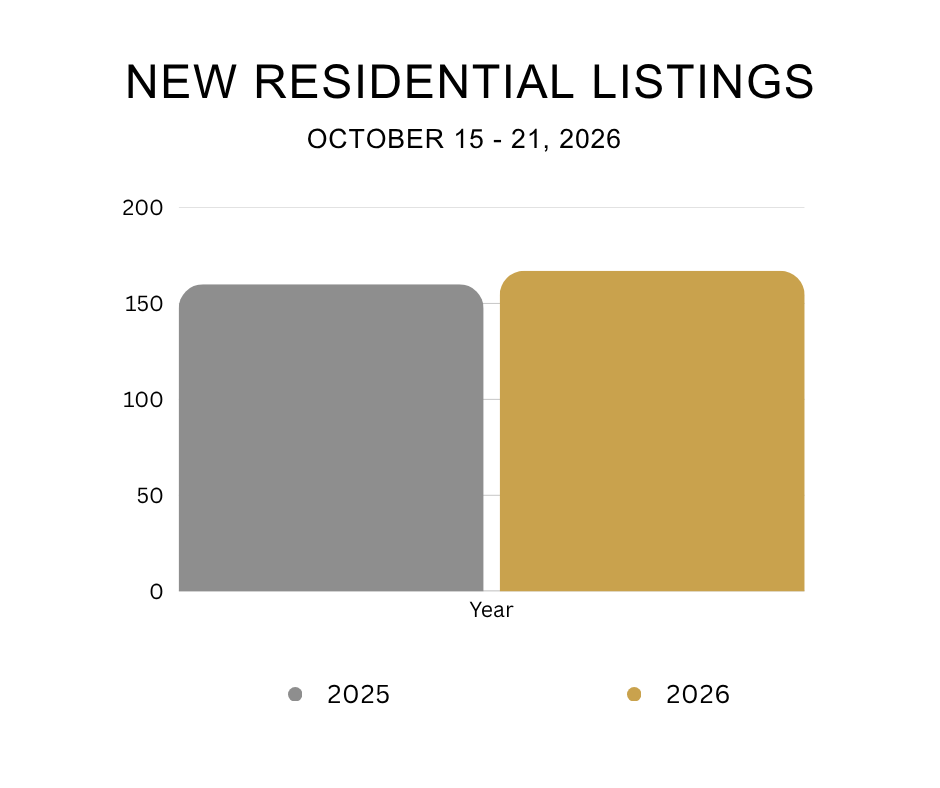
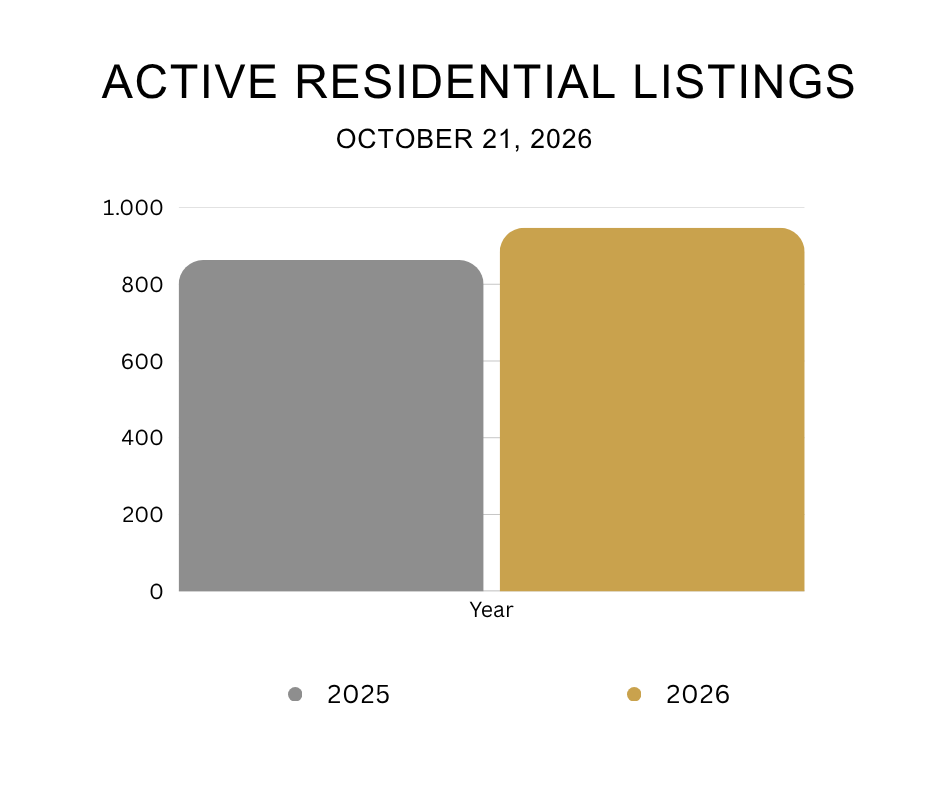
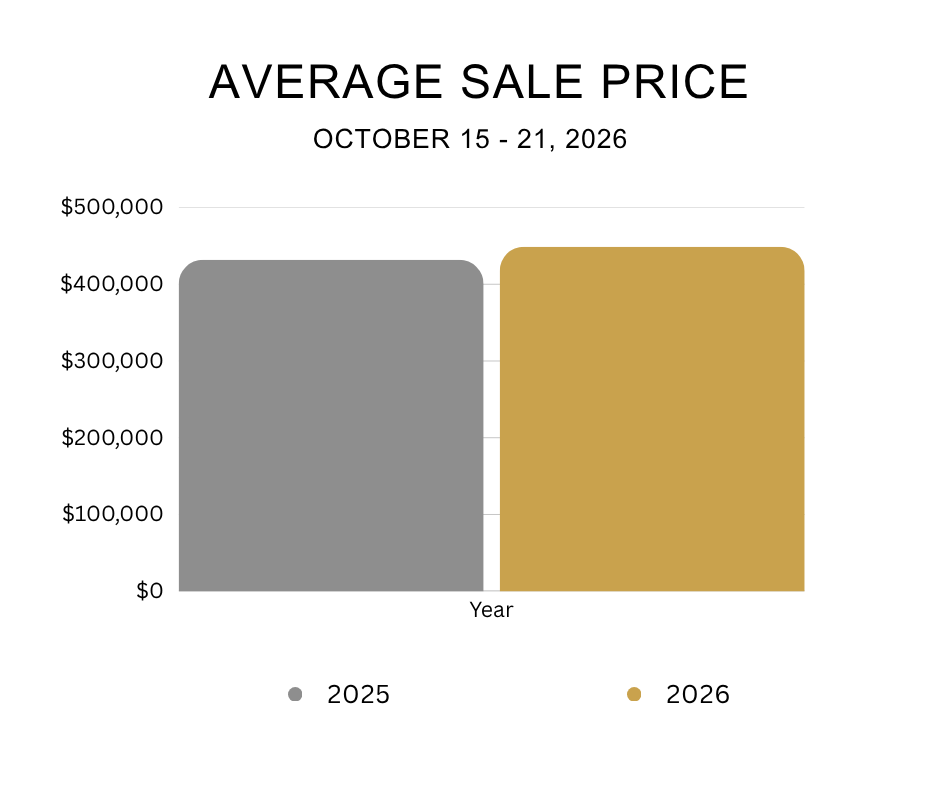
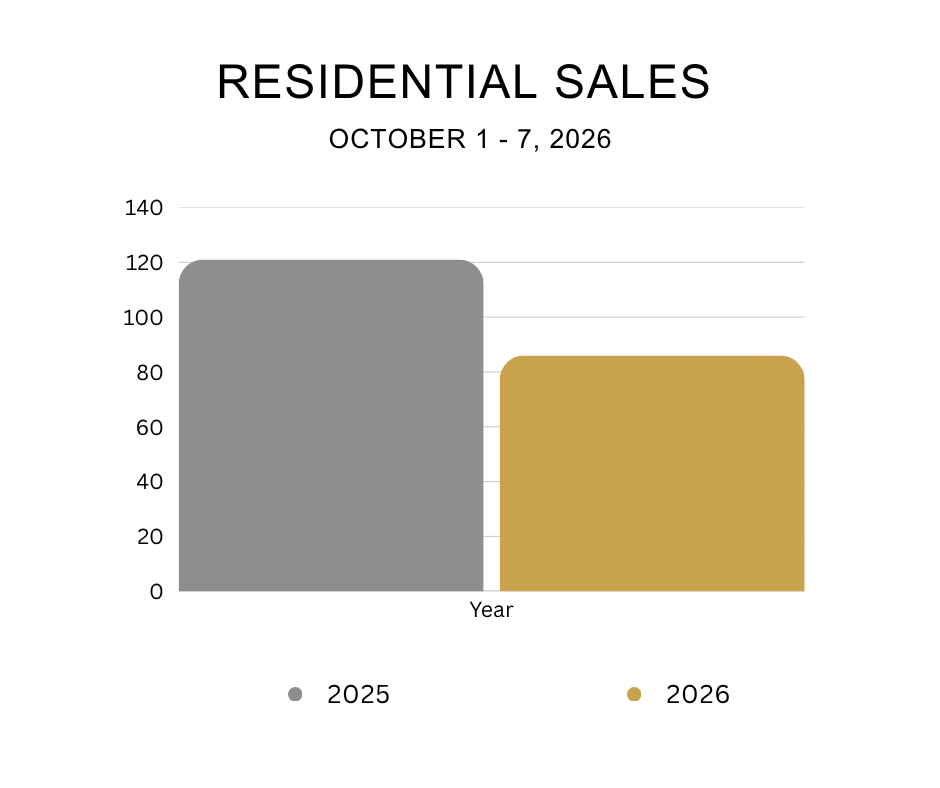
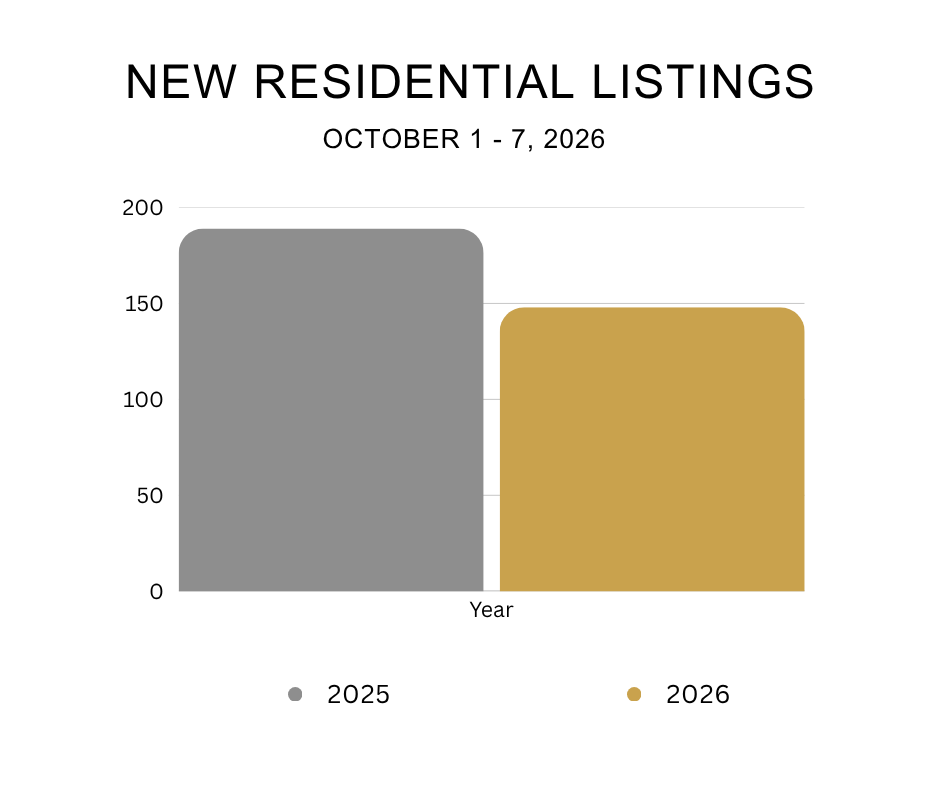
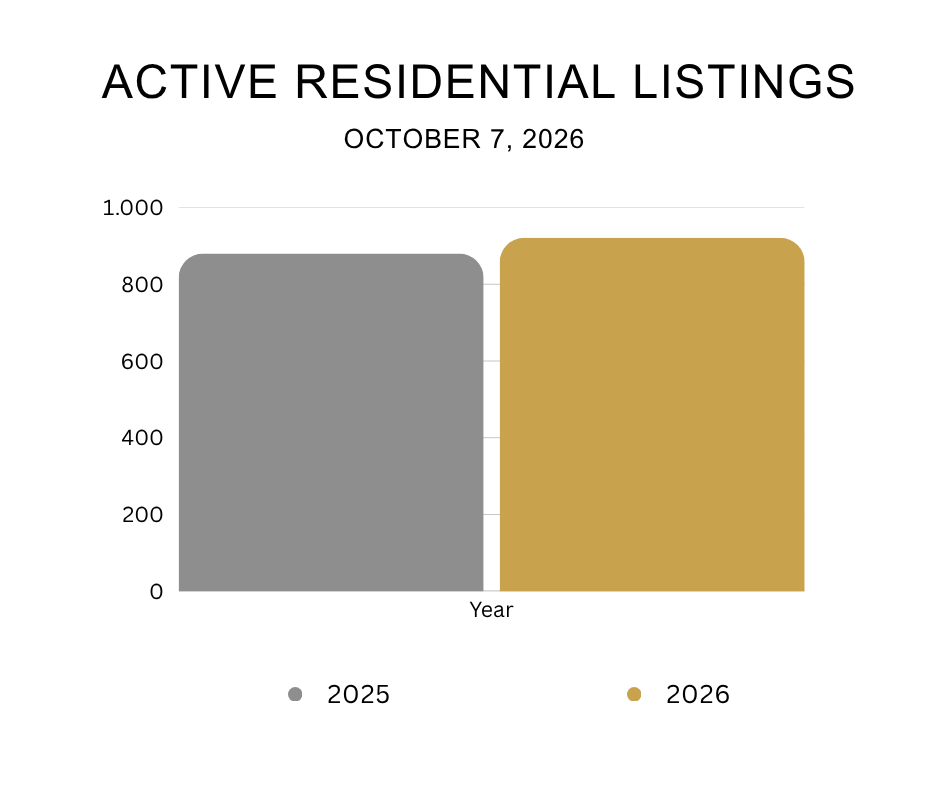
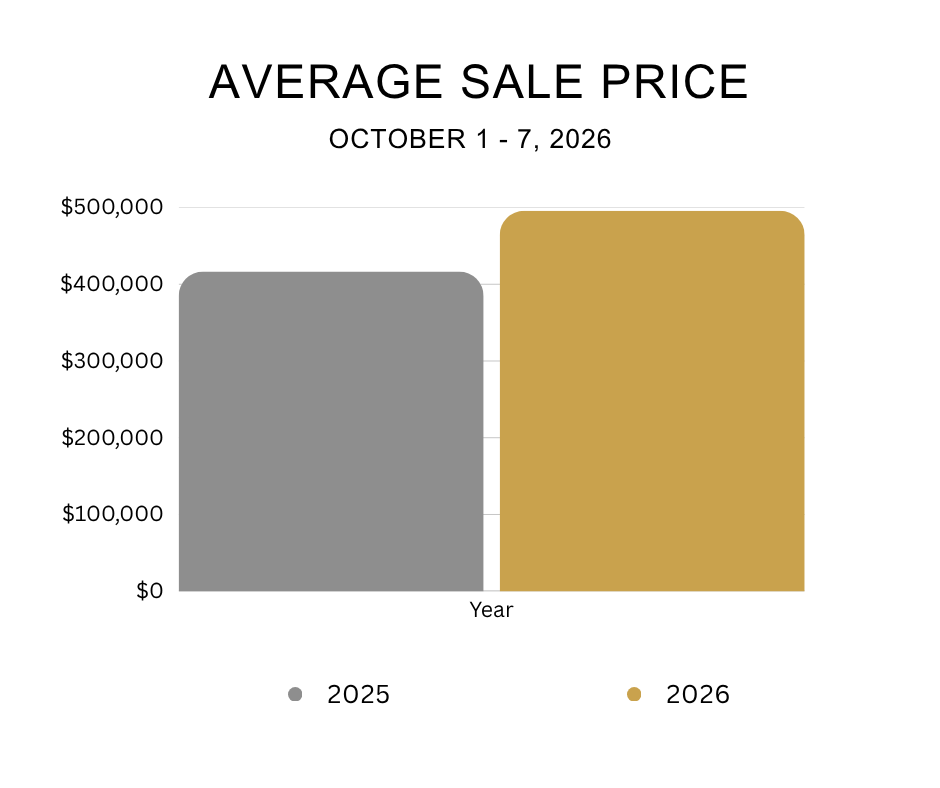
October 28, 2026 | Irwin Realty & Associates
After more than three years without an interest rate increase, the Bank of Canada has officially changed direction.
On October 28, 2026, the Bank of Canada announced a 0.25 percentage point increase to its benchmark interest rate, bringing it from 2.25% to 2.50%.
This marks the first rate hike since July 2023, following a lengthy period of rate cuts and stability.
While a quarter of a percentage point might not sound particularly dramatic, the decision signals a shift in the Bank's approach to managing inflation and the Canadian economy.
For homeowners, prospective buyers, and sellers in Saskatoon, it raises some important questions.
Will mortgages become more expensive? Could housing prices be affected? And is now still a good time to buy or sell?
Let's take a closer look.
Why Did the Bank of Canada Raise Interest Rates?
The Bank of Canada's primary responsibility is to keep inflation under control while supporting a stable Canadian economy.
After raising interest rates throughout 2022 and 2023, the Bank began reducing its benchmark rate in June 2024 as inflation pressures eased.
By October 2025, the rate had fallen to 2.25%, where it remained for nearly a year.
Now, the Bank has reversed course.
Inflation has proven more persistent than expected, with higher global energy prices contributing to increased costs for consumers and businesses.
The Bank is concerned that these pressures could spread throughout the broader economy, making everyday goods and services more expensive.
At the same time, economic activity has shown resilience, giving policymakers more room to address inflation through higher interest rates.
Today's increase is intended to help prevent elevated inflation from becoming more widespread.
The Bank has also indicated that further increases could be necessary, although future decisions will depend on how economic conditions develop.
What Does This Mean for Saskatoon Homebuyers?
If you're thinking about buying a home in Saskatoon, today's announcement could affect your borrowing costs and overall purchasing power.
Variable-rate mortgages are particularly sensitive to changes in the Bank of Canada's overnight rate, as lenders generally adjust their prime lending rates in response.
For example, consider a $400,000 mortgage with a 25-year amortization.
If the mortgage interest rate increases from 4.00% to 4.25%, the approximate monthly payment would rise from $2,104 to $2,165.
That's an increase of about $61 per month, or $732 annually.
This is an illustrative calculation. Actual payments depend on your mortgage terms, payment frequency, and lender. Some variable-rate mortgages have fixed payments that may not immediately increase.
For buyers already managing tight budgets, even a modest increase can make a difference.
Is Now Still a Good Time to Buy?
Potentially, yes.
Interest rates are an important consideration, but they're only one part of the homebuying equation.
Buyers should also consider:
Available inventory in their preferred neighbourhoods
Current asking prices compared with recent sales
Opportunities to negotiate on price or conditions
Their financial situation and long-term housing needs
The affordability of mortgage payments and other ownership expenses
In Saskatoon, market conditions can vary considerably depending on the neighbourhood, price range, and property type.
We've also seen periods when buyers have had more opportunities to negotiate, particularly as inventory levels and market activity change throughout the year.
A higher interest rate doesn't necessarily eliminate good buying opportunities. It simply makes careful budgeting and informed decision-making more important.
What About Current Homeowners?
If you already own a home, the impact of today's announcement depends largely on your mortgage structure.
Variable-rate mortgages
If you have a variable-rate mortgage, your lender may increase your interest rate following the Bank of Canada's decision.
Depending on your mortgage terms, this could mean a higher monthly payment or a larger portion of your existing payment going toward interest.
Fixed-rate mortgages
If you have a fixed-rate mortgage, your current rate and scheduled payments generally remain unchanged until your mortgage term ends.
However, homeowners approaching renewal should pay attention to available mortgage rates and review their options well before their renewal date.
Home equity lines of credit
Many home equity lines of credit are tied to a lender's prime rate. As prime rates rise, borrowing costs on these products may also increase.
If you're uncertain how today's announcement affects your mortgage, speaking with your lender or mortgage professional is a good place to start.
Will Higher Interest Rates Cause Saskatoon Home Prices to Fall?
This is likely one of the biggest questions on buyers' and sellers' minds.
Higher borrowing costs can reduce purchasing power, potentially causing some buyers to lower their budgets or delay their plans.
That can influence housing demand.
However, higher interest rates don't automatically mean lower home prices.
Saskatoon's real estate market is influenced by several local factors, including:
The number of homes available for sale
Population growth and housing demand
Employment and economic conditions
New home construction
Buyer activity across different price ranges
A well-priced home in a desirable neighbourhood may continue to attract strong interest, even when borrowing becomes more expensive.
Conversely, properties priced above current market expectations may take longer to sell or require adjustments.
This is why it's important to look beyond national headlines and understand what's happening in Saskatoon's local housing market.
What Should Saskatoon Sellers Do?
If you're considering selling your home, today's announcement reinforces the importance of accurate pricing and effective marketing.
As buyers become more conscious of their budgets, they're likely to pay closer attention to value.
For sellers, that means understanding how your home compares with competing properties and what buyers are actually willing to pay.
A successful selling strategy should include:
Pricing based on current comparable sales
Professional photography and strong online marketing
Preparing your home to make a positive first impression
Understanding your competition
Remaining flexible as market conditions change
A changing interest rate environment doesn't mean it's a bad time to sell. It means having the right strategy becomes even more valuable.
Should You Wait for Interest Rates to Come Down?
Trying to perfectly time the housing market is difficult.
Interest rates may rise, fall, or remain unchanged in the coming months, and housing prices don't always move in the same direction.
Waiting for lower borrowing costs could potentially reduce mortgage payments, but changes in housing prices or available inventory could offset those savings.
For buyers, the more important question is whether purchasing a home makes sense for their finances and long-term plans.
For sellers, it's whether current market conditions align with their goals and timeline.
Neither decision should be based solely on one interest rate announcement.
The Bottom Line: Stay Informed, Not Alarmed
After more than three years without an increase, the Bank of Canada's decision to raise its policy rate to 2.50% represents an important shift.
It's certainly worth paying attention to, particularly if you're planning to purchase a home, renew your mortgage, or access home equity.
But one interest rate announcement doesn't determine the direction of Saskatoon's housing market.
Local inventory, buyer demand, pricing trends, and individual circumstances continue to play an important role.
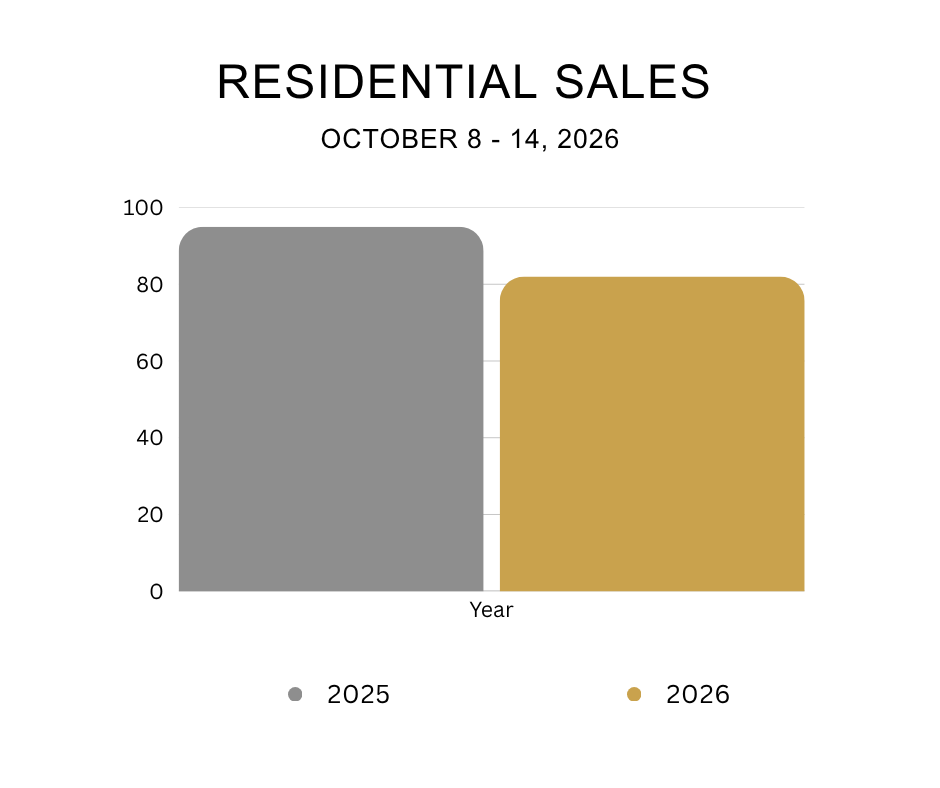
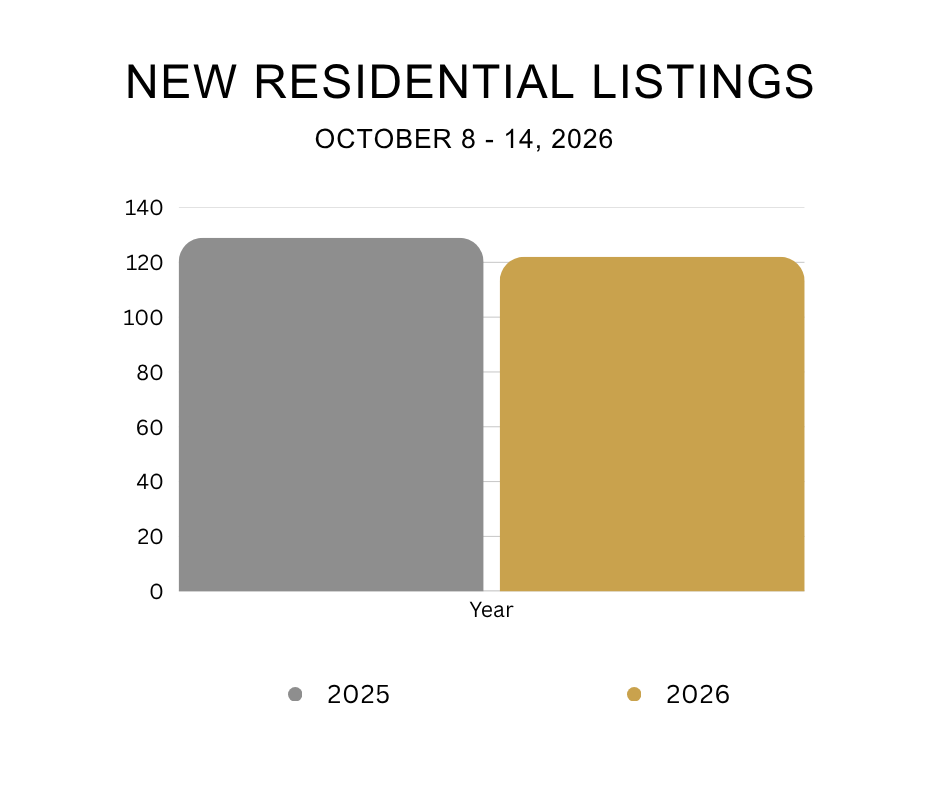
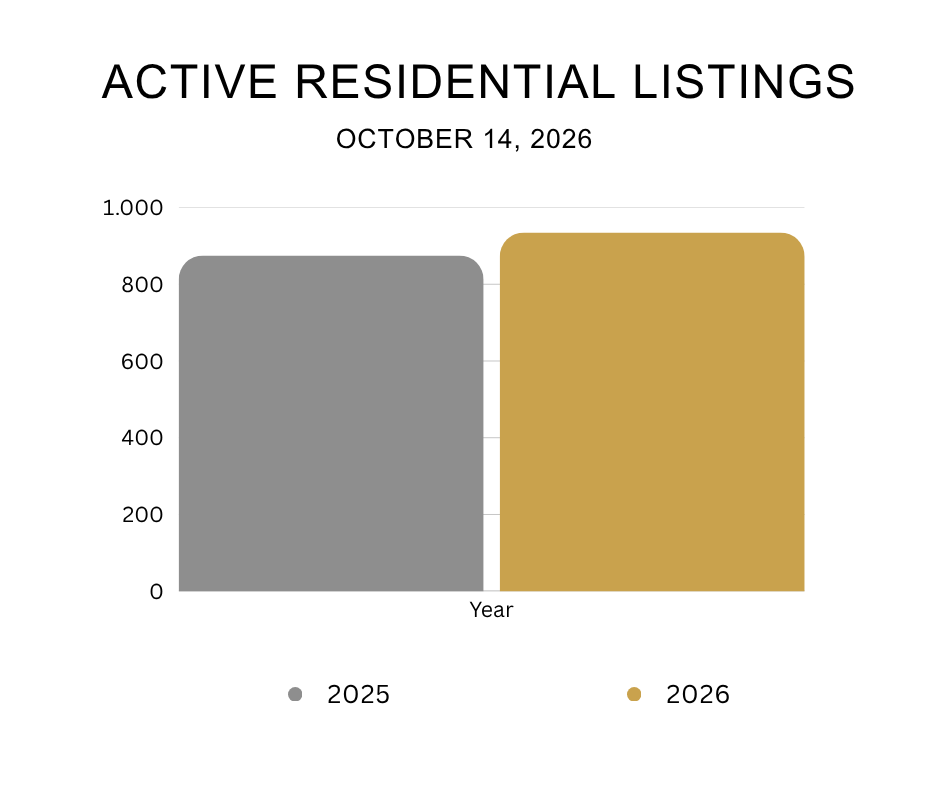
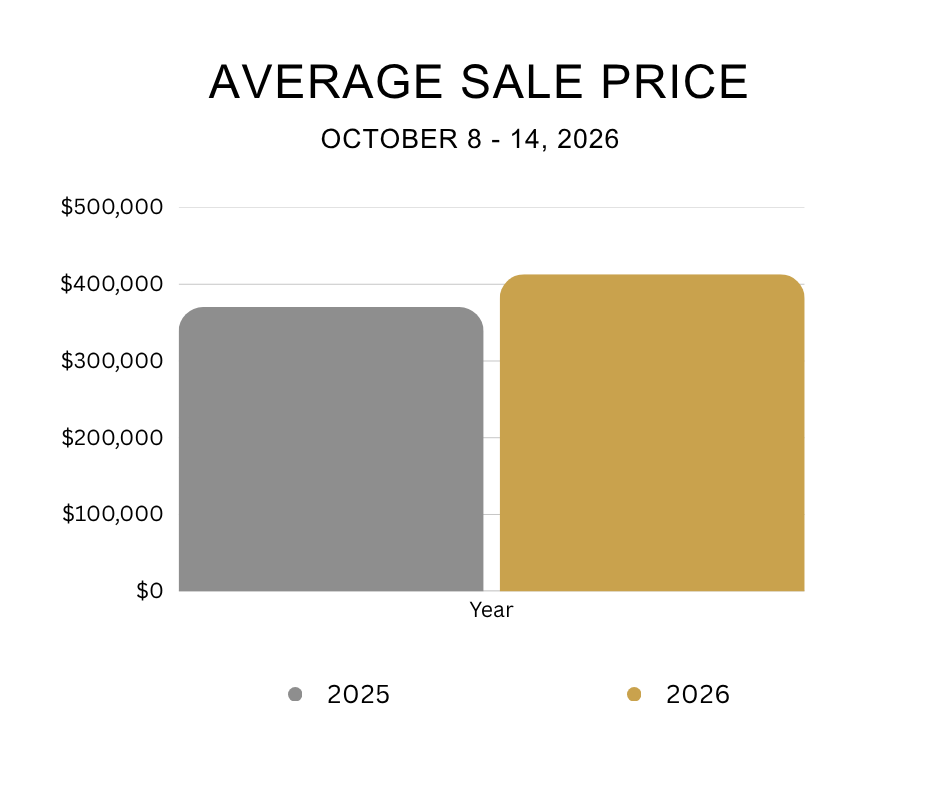
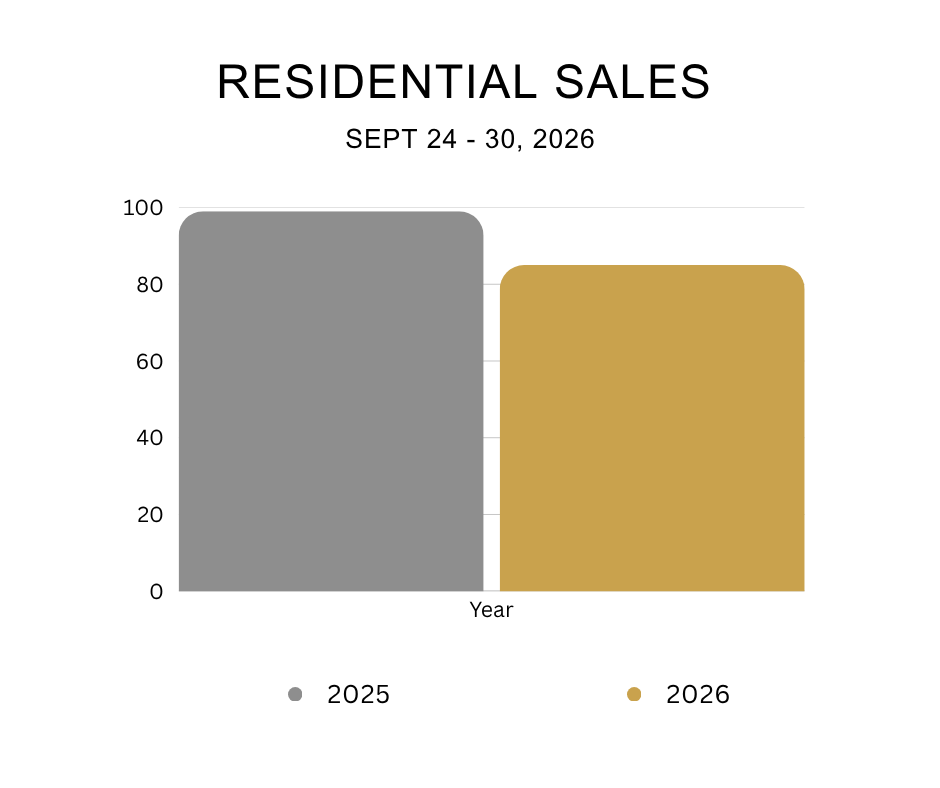
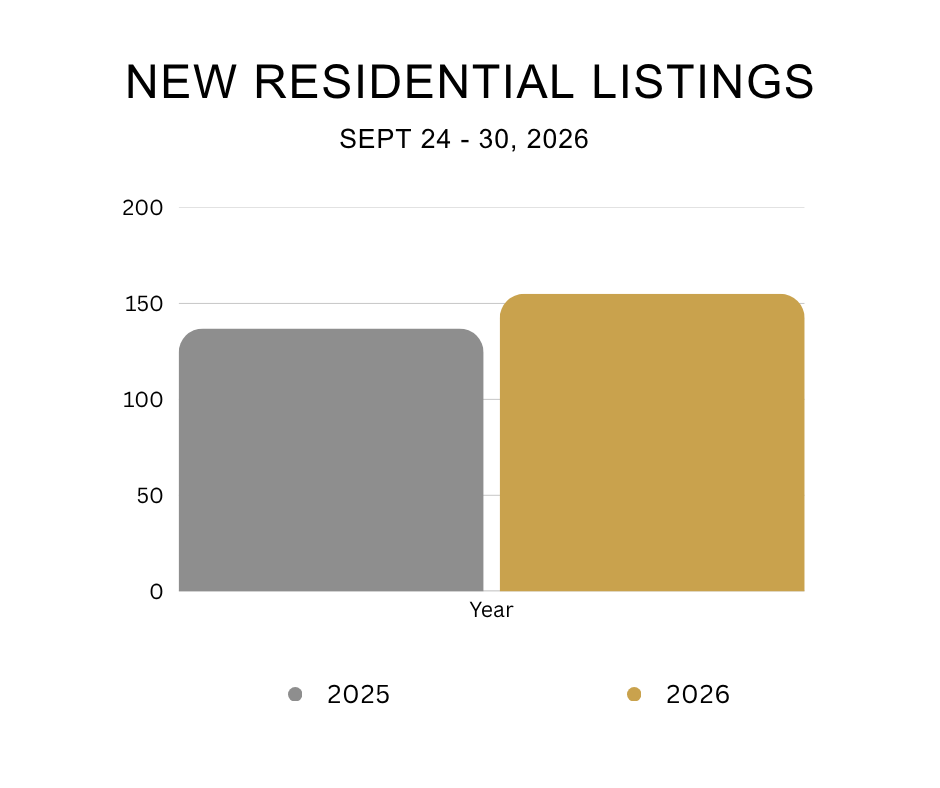
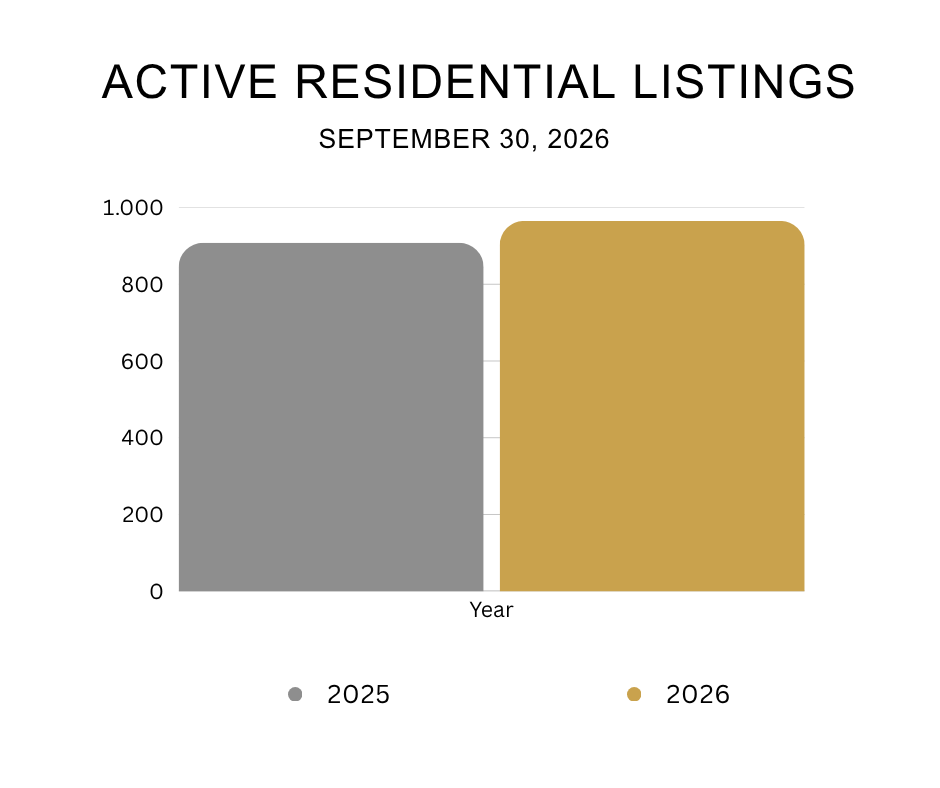
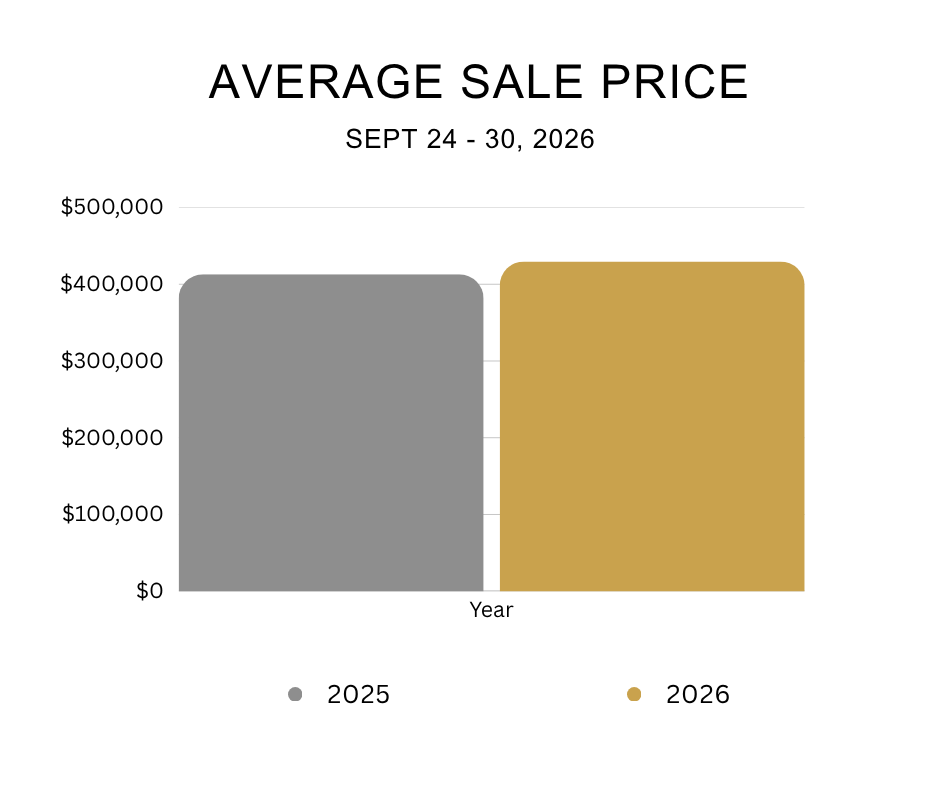
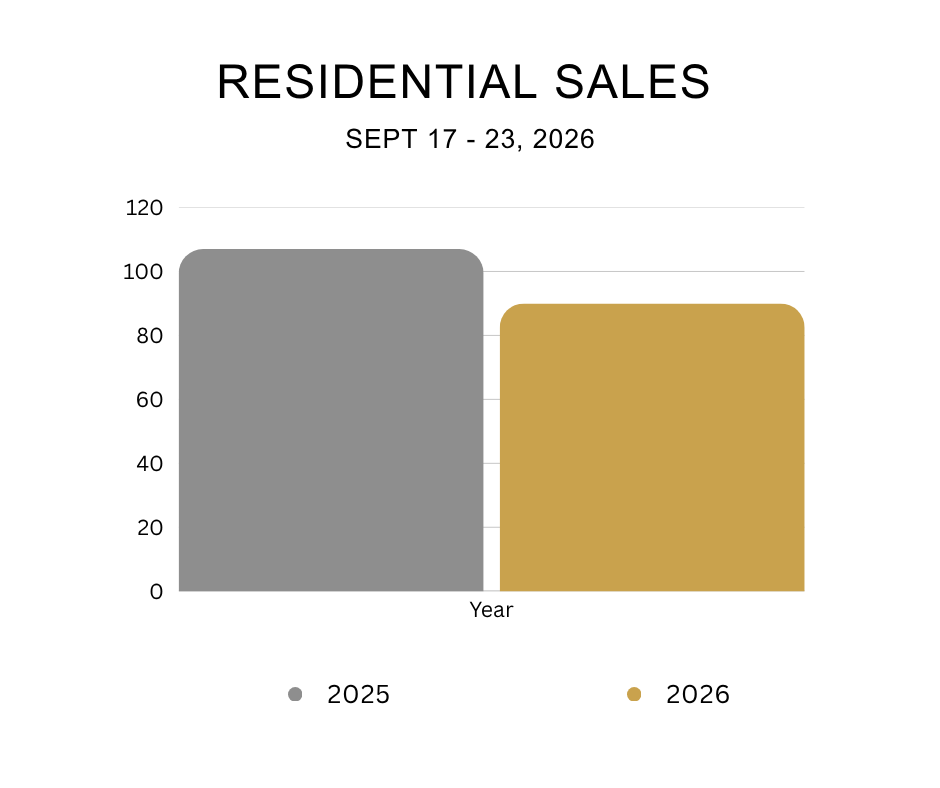
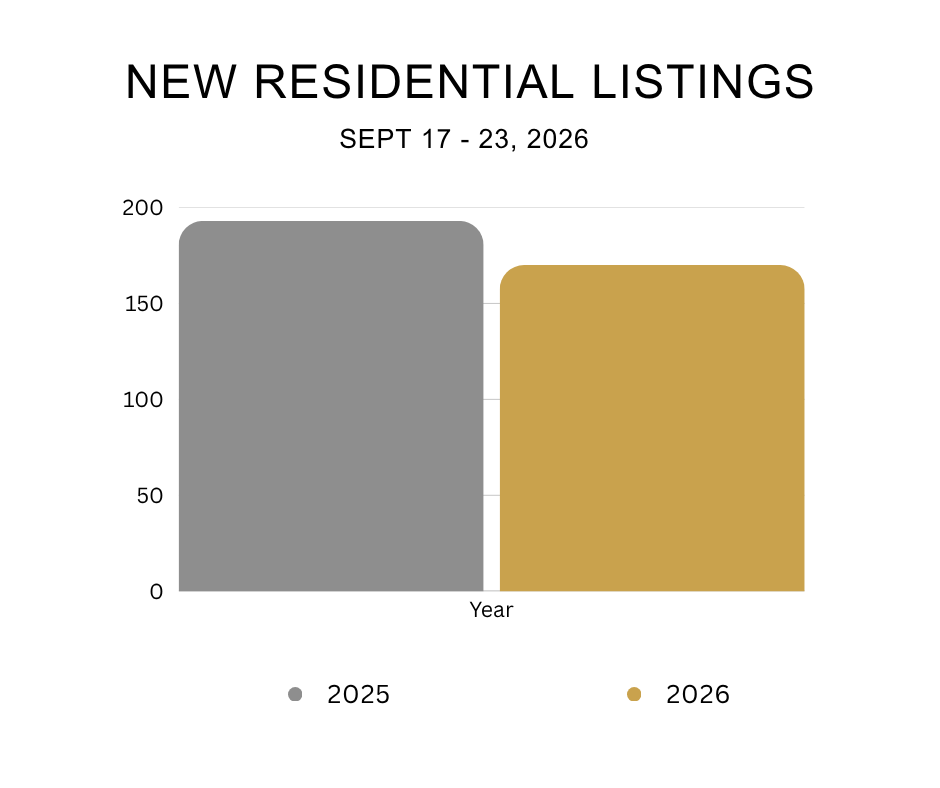
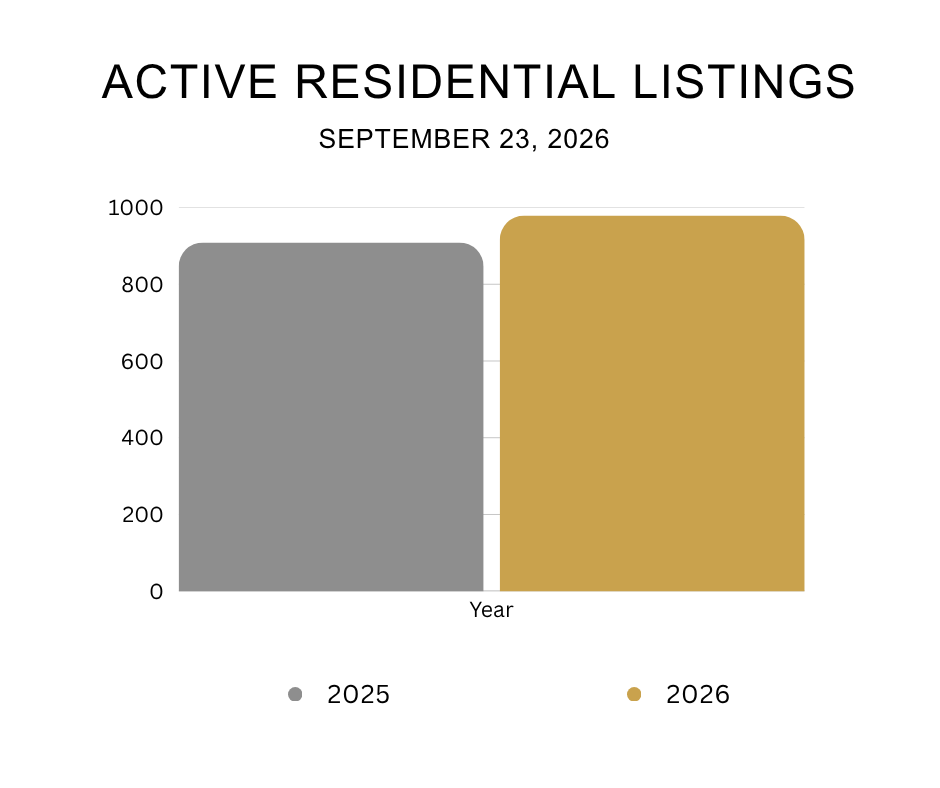
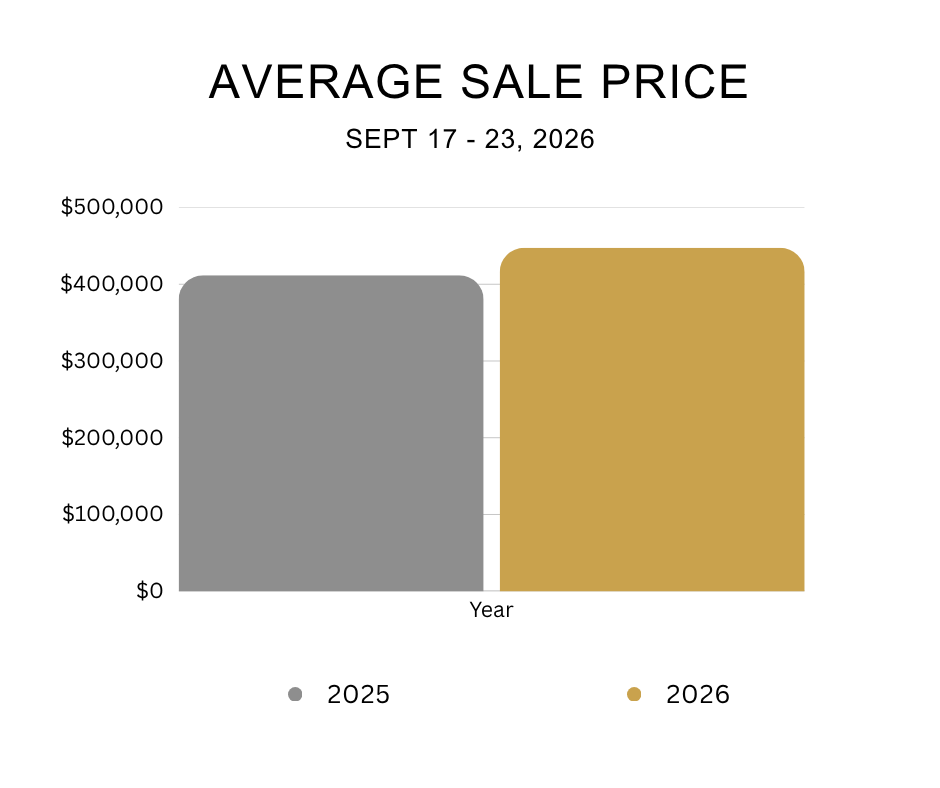
At Irwin Realty & Associates, we follow Saskatoon's real estate market closely through our weekly market reports, tracking sales, new listings, available inventory, and pricing trends.
Our goal is to help you understand what those numbers mean so you can make informed real estate decisions with confidence.
Thinking About Buying or Selling in Saskatoon?
Whether you're ready to make a move or simply want to understand how changing market conditions could affect your plans, we're here to help.
Scott Irwin and Derrick Brucks of Irwin Realty & Associates would be happy to discuss your options and provide insight into Saskatoon's current real estate market.
Visit scottirwinrealty.com to connect with our team.
Thanks for following along,
Irwin Realty & Associates
Royal LePage Saskatoon Real Estate